The essential information
Whatever the country, a compliant invoice identifies who sells, who buys, what is sold, when and for how much. In practice:
- The word “Invoice” and a unique number that follows a continuous chronological sequence (for example FA26-0001, FA26-0002…). Never reuse or skip a number.
- The issue date and, when different, the date of delivery or of the service.
- Your business: legal name, address and legal/tax identifiers.
- Your client: name and address, and for a business client its identifiers when the law requires them.
- Each line: precise description, quantity, unit, unit price excluding tax, discount if any.
- The applicable tax rate(s), the tax amount per rate, and the totals excluding and including tax.
- The payment terms: due date, accepted payment methods, and late-payment conditions where required.
Using the tool step by step
The numbered marks on the screenshots follow the order in which you use the tool. The fields are filled with an example.
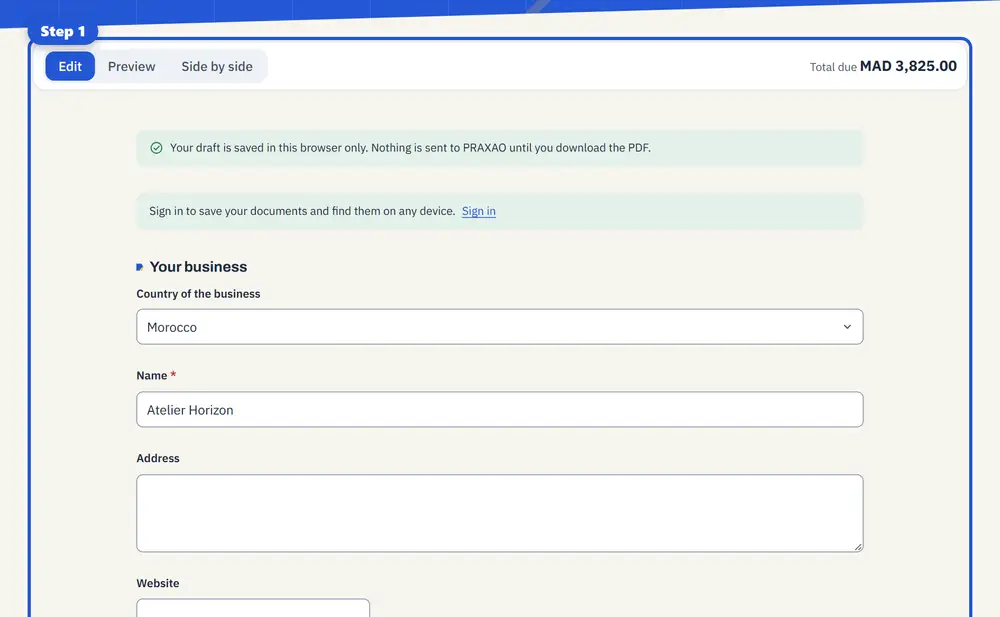
Step 1 Enter your values: dimensions, materials and options. 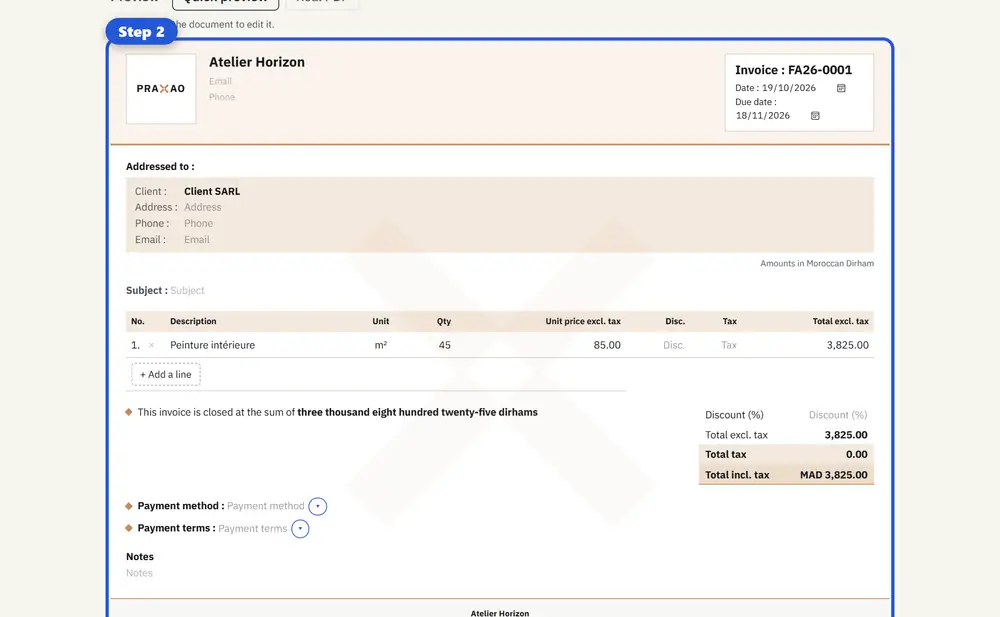
Step 2 Check the preview of the document as it will be sent. 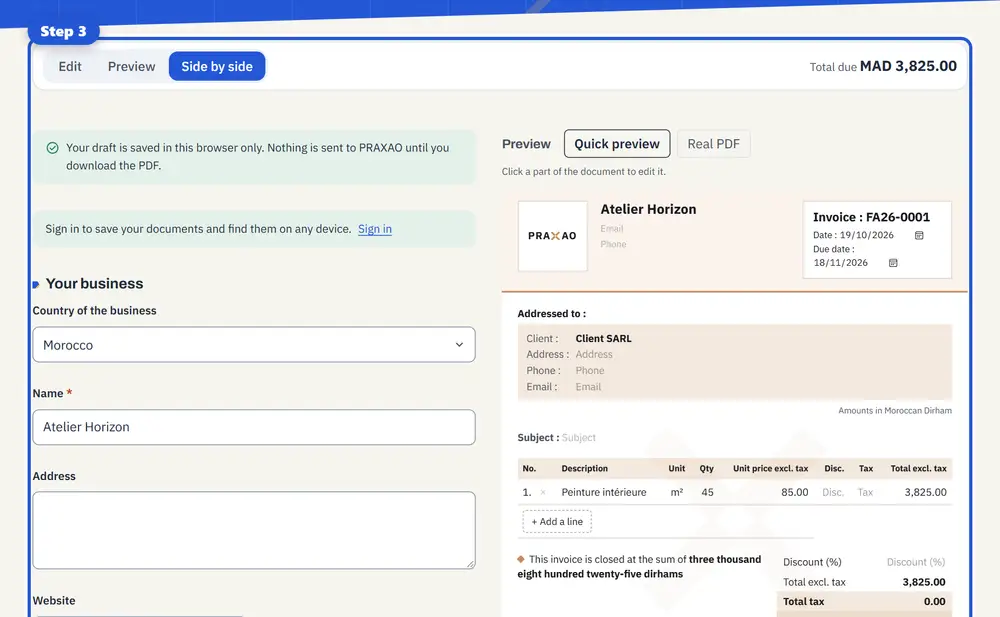
Step 3 Edit the fields and watch the document update side by side.
Morocco
Invoices must show the Identifiant Commun de l’Entreprise (ICE) of the seller and, for business clients, the ICE of the buyer. Also show your Identifiant Fiscal (IF), Registre du Commerce (RC) number and, commonly, the taxe professionnelle (patente) and CNSS numbers.
The standard VAT rate is 20 %, with reduced rates of 7 %, 10 % and 14 % for certain goods and services. It is customary to state the total in words (“Arrêtée la présente facture à la somme de…”).
France
Show the SIREN or SIRET number, the legal form and share capital for companies, and the intra-community VAT number when you have one. Standard VAT is 20 % (reduced 10 %, 5.5 % and 2.1 %).
Between businesses, the invoice must state the payment due date, the late-payment penalty rate and the fixed €40 recovery indemnity. A micro-entrepreneur exempt from VAT writes “TVA non applicable, art. 293 B du CGI”.
Spain and Germany
In Spain, invoices show the NIF of both parties, a correlative number and IVA at 21 % (reduced 10 % and 4 %).
In Germany, a Rechnung needs the Steuernummer or USt-IdNr, a unique invoice number, the date of supply (Leistungsdatum) and USt at 19 % or 7 %. Small businesses under §19 UStG state that no VAT is charged.
Good habits
Keep the same numbering sequence for the whole year, send invoices as PDF, and keep a copy for the legal retention period (often 10 years). Correct a mistake with a credit note rather than by modifying an issued invoice.
This guide is general information: rules change and depend on your activity. Check with your accountant or tax administration for your case.
General information, checked at the date shown. It does not replace advice from a professional for your situation.